
IndiaFilings
Expert
Published on: Sep 25, 2026
GST Input Tax Credit Scheme for Existing Stock
The Ministry of Finance (MoF) announced the GST Input Tax Credit (ITC) scheme in the Transitional Provisions rules to provide GST Input Tax Credit for unregistered persons. This scheme covers unaccounted goods or stock on hand during the GST rollout. In this article, we delve into the GST Input Tax Credit Scheme for unregistered taxpayers and existing stock in detail.
GST Input Tax Credit for Central Excise
The GST input tax credit scheme for Central Excise mentioned in the Transitional Provisions rules targets unregistered persons lacking existing registrations, such as central excise registration, or evidence of central excise duty payment while holding stock as of the GST implementation date.
The Ministry allows such persons to claim GST ITC on goods held in stock. Central excise or additional customs duties apply on the GST implementation date after central tax payment. The framework permits a 60% tax rate on goods that attract central tax at 9% or more. For other goods, the central excise tax rate applies at 9% or less, and GST input tax credit is allowed at 40%. Upon integrated tax payment on these goods, the input tax credit is 30% and 20%, respectively. The system credits the GST input tax to the taxpayer's electronic credit ledger after central tax payable on such supply.
Conditions to Avail ITC
The person shall follow the conditions below to avail the ITC under this scheme:
- Goods unconditionally exempted from the whole of the duty of excise as specified in the First Schedule to the Central Excise Tariff Act, 1985, with nil-rated applicable goods in the said Schedule.
- The registered person shall procure the necessary documents and maintain records for the said goods.
- The registered person using this scheme should furnish stock details via a statement in FORM GST TRAN 2. At the end of each of the six tax periods, taxpayers must detail the stock to indicate the scheme's applicability for supply of goods during the tax period.
- The system will credit the amount of credit to the electronic credit ledger maintained in FORM GST PMT-2 on the Common Portal.
- The concerned individual must store the stock details so registered persons can easily identify them.
The scheme for claiming GST input tax credit against central excise will be available for six months from the GST implementation date.
GST Input Tax Credit for VAT
Any taxpayer with VAT registration holding stock on the GST implementation date, where VAT payment occurred at the first point of sale in the State and subsequent sales are not state-taxable, can avail GST input tax credit even in the absence of a value-added tax payment document.
The Act allows the GST input tax credit for such goods at a 60% rate for goods with state tax at 9% or more. For goods with state tax at 9% or less, the input tax credit applies at 40%. If integrated tax is paid on these goods, the credit amount is 30% and 20%, respectively. GST input tax credit credits to the electronic credit ledger after the payment of state tax on such supply.
Conditions to Avail GST ITC
The concerned individual must meet the following criteria to claim the GST input tax credit under this scheme:
- Only part of the goods is exempt from the Value Added Tax Act of the concerned state.
- The registered person must procure the documents for such goods and have them available on records.
- The registered person using this scheme should submit a stock statement in FORM GST TRAN 2 at the end of each of the six tax periods, indicating the scheme's operation with supply details during the tax period.
- The allowed credit amount is credited to the electronic credit ledger maintained in FORM GST PMT-2 on the Common Portal.
- The stock of goods on which the credit is availed must be stored so it can be easily identified by the registered person.
The scheme for claiming GST input tax credit against VAT is available for six months from the GST implementation date.
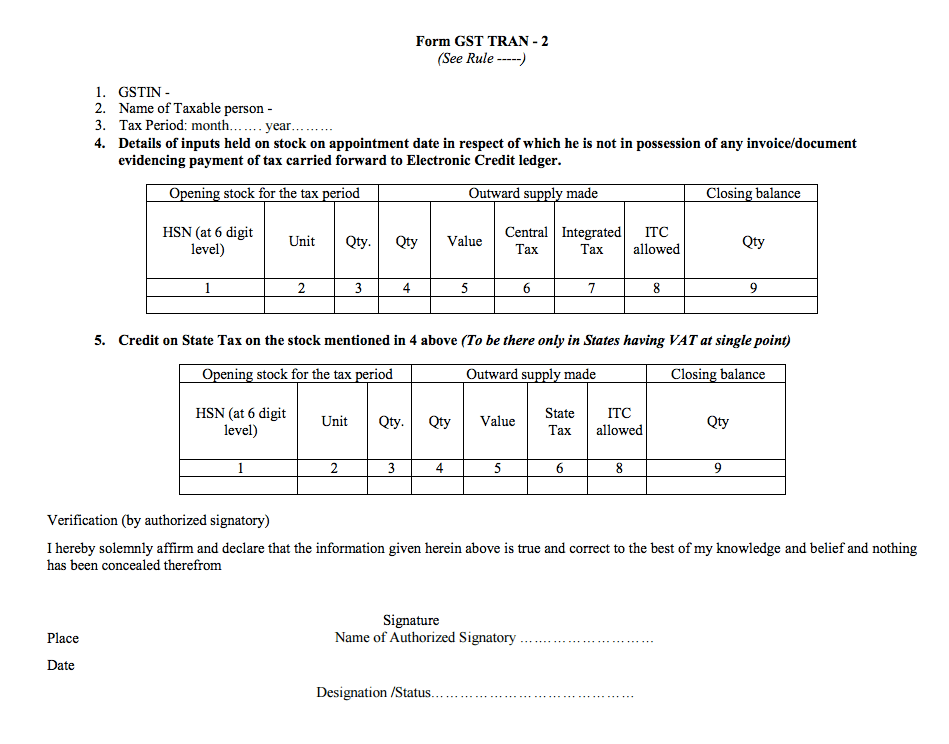 GST TRAN-2 Form
GST Transitional Rules
To learn more about the details on availing the GST ITC scheme under GST Transitional Rules, refer to GST Input Tax Credit, GST Input Tax Credit FAQs, and the GST Transitional Rules PDF document.