
Sreeram Viswanath
Expert
Published on: Sep 15, 2026
Form INV-01: Understanding Its Significance in the GST Regime
Form INV-01 holds a pivotal role in the Indian GST regime due to its provision for generating the Invoice Reference Number (IRN). The IRN serves as a digital alternative to traditional invoicing systems, where the buyer maintains the original invoice, a duplicate is issued to the transporter, and a triplicate is given to the seller. This digital approach streamlines revenue processes at check posts, reduces waiting times for transporters, and allows tax authorities to track goods without relying on duplicate copies. Furthermore, the absence of a physical invoice mitigates the risk of loss.
The IRN can be generated from the eway bill portal by uploading an invoice using Form GST INV-01. Once generated, this number is valid for 30 days and can replace a physical tax invoice during this period. This article delves into Form GST INV-01 and its particulars.
Format Explained: Navigating Form GST INV-01
To generate the IRN, GST INV-01 must be uploaded to the portal. The form is divided into four parts, each requiring specific details. Below is a detailed breakdown:
Part A: Supplier's Details
- GSTIN and name of the supplier (auto-populated).
- Address of the registered/principal business location.
- Serial number and date of invoice.
These details ensure correct identification and are integral for CA-assisted GST return filing.
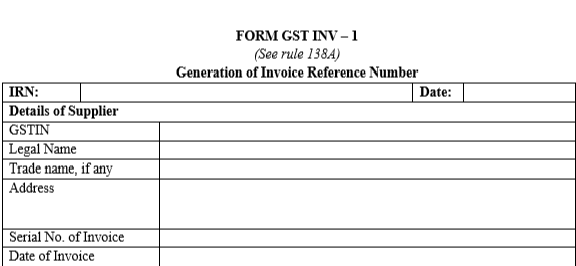 Form GST INV 1 - Part A
Part B: Recipient's Details
- GSTIN (for registered taxpayers).
- UIN (for embassies or UN organizations).
- Name of the recipient and consignee.
- Consignee's address and state code (first two digits of the GSTIN).
The recipient's and consignee's details are crucial for tracking purposes. It's important to note that these two entities might have the same GSTIN but different addresses if annual GST returns are required.
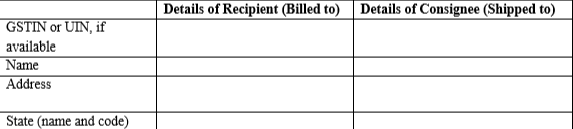 Form GST INV Part B
Part C: Type of Supply
Part C covers details regarding the type of transaction and its tax implications. This information determines the applicability of specific tax provisions and due dates for GST filings.
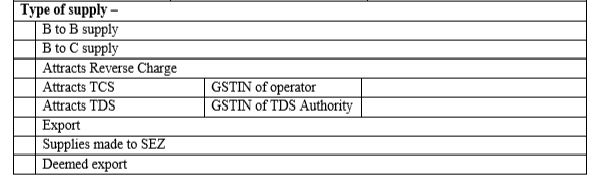 Form GST INV 1 - Part 3
Part D: Consignment Details
- Description of goods.
- HSN code.
- Quantity and unit price, pivotal for determining the taxable GST amount.
- Applicable tax rate and amount, calculated based on the type of transaction (inter-state or intra-state).
- Declaration of freight, invoice, packaging, and forwarding charges as stated in the tax invoice.
Full transparency and accuracy in Part D are essential for online GST filing.
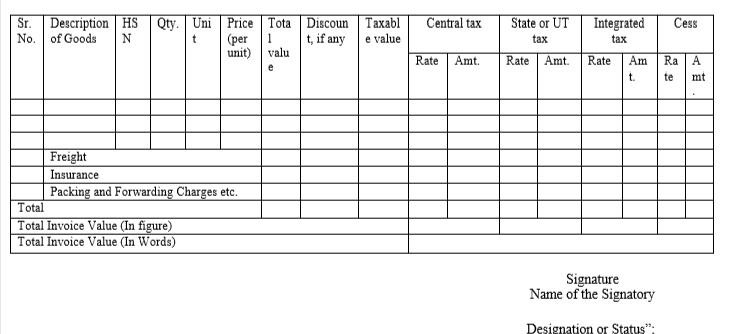 Form GST INV 1 - Part D
HSN Code: The Harmonized System Nomenclature Code is an internationally recognized classification method employed by the Indian Government for categorizing goods under GST, aiding in accurate tax levy.
In conclusion, understanding the intricacies of Form GST INV-01 is crucial. This form plays a significant role in streamlining the GST invoicing process, ensuring compliance with tax regulations, and optimizing the ITC reconciliation process.